YNAB

- 4.53K Reviews
- 4.6
- Downloads
- 1,000,000+
 Analysis by Mobxio
If you’re anything like me, managing money can sometimes feel like juggling flaming torches. Enter YNAB, or "You Need a Budget," which is here to make sure you don’t set your finances on fire. I’ve taken it for a spin, and here’s what I think.
What to expect from a different kind of budget
YNAB is a finance app from ynab.com built around making decisions with the money you already have, rather than treating a budget as a forecast of money that might arrive later. Its zero-based approach asks you to give available dollars specific jobs. That can sound strict at first, but I find the useful idea is not that every choice must be perfect; it’s that you decide what matters before routine spending quietly decides for you.
The app is free to install, with in-app purchases listed from $14.99 to $109.00 per item. That distinction matters if you’re comparing it with a basic spreadsheet or a free expense tracker: downloading it does not necessarily mean every part of the service is free. I’d check the current purchase details before building a long-term routine around it. For a first-time user, the most important question is whether you want an active budgeting method, not just a place to look at transactions.
Its audience is broad: the app is rated for Everyone, has a 4.6 average from around 23,000 ratings, and has passed 1 million installs. It first appeared on October 20, 2015, and version 25.37.2 requires Android 10 or later. Those figures give a sense of its established presence, but they don’t tell you whether its hands-on style fits your habits. I’d choose it for deliberate planning; I wouldn’t choose it just to glance at a monthly spending pie chart.
Getting Started with YNAB
I’d begin by treating the first budget as a working draft, not a test you have to pass. In this section, I’ll focus on making the initial choices feel manageable, so you can get to a useful plan without trying to account for every possible expense at once. A small, realistic setup is easier to revisit and improve.
Set up a budget you can actually use
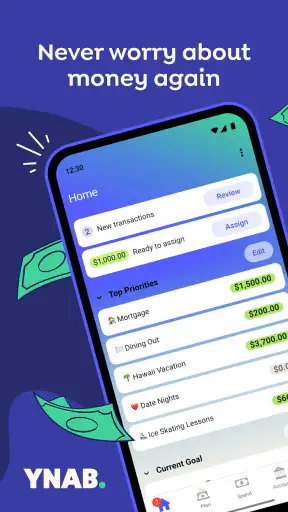
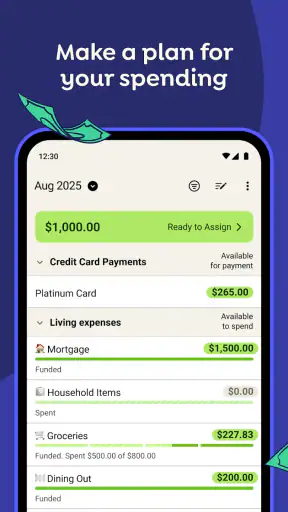
First things first, setting up YNAB is a breeze. After downloading the app, you’re guided through the setup with a friendly tutorial that makes budgeting almost feel fun. Almost. The app uses a method they call "zero-based budgeting," where every dollar has a job. This approach encourages you to allocate each dollar towards a specific goal, whether it’s bills, savings, or that new gadget you’ve been eyeing.
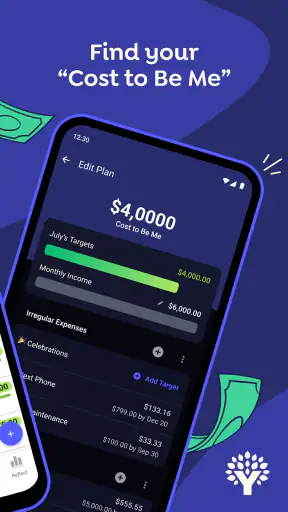
My practical advice is to start with categories that reflect decisions you already make: housing, groceries, transport, recurring bills, and a small amount for flexible spending. Don’t try to build a perfect map of your financial life on the first screen. A budget is easier to maintain when its labels match the way you think, and you can refine it after seeing a few real weeks of spending. If you have irregular costs, give them their own place rather than letting them appear as surprises. Car maintenance, annual renewals, and gifts are common examples of expenses that feel occasional but are predictable enough to plan for.
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
Before assigning money, take a moment to distinguish money you have now from income you expect later. That is the central habit this method asks for. If you budget against a hoped-for paycheck, the plan can look reassuring while still leaving today’s bills uncovered. Starting with what is available makes the first pass more honest, even if that means some categories wait until more money arrives.
Make the first useful decision
A meaningful first win doesn’t have to be a dramatic savings milestone. It can be looking at the money currently available, covering the next bill that matters, and deciding how much can safely go toward groceries until your next income arrives. That small exercise turns the budget from a set of intentions into a practical answer to “Can I afford this today?” I’d use that question before a discretionary purchase, then update the plan if priorities change.
Picture an ordinary weekday: you’re about to pick up groceries, and you also remember that a bill is due soon. Rather than relying on your bank balance alone, check the amount assigned to groceries and compare it with what remains after the bill is accounted for. If the grocery category is tight, you can choose a cheaper shop or move money from a less urgent category. That trade-off is the point; the app doesn’t make the decision for you, but it helps you see what you are choosing.
When spending differs from the plan, treat that as information rather than failure. If you overspend in one category, adjust the budget by moving money from another category you’re willing to reduce. This is more useful than hiding the overspend or abandoning the whole month. In my view, learning to make that adjustment calmly is one of the best early signs that the method is becoming workable.
Features That Stand Out
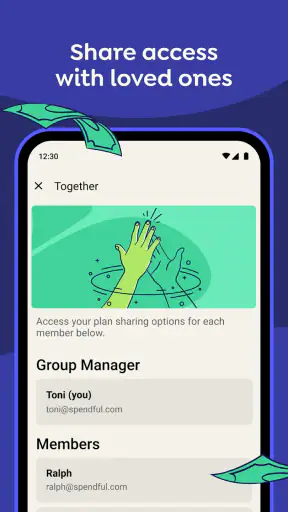
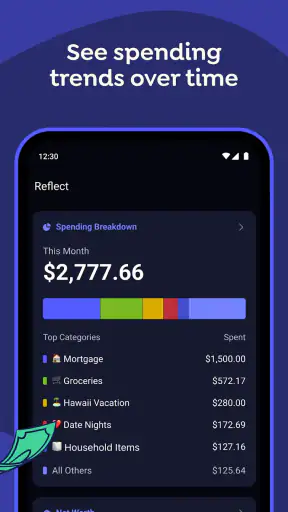
One feature that really caught my attention is the real-time sync. Whether you’re on your phone or computer, your budget updates automatically. This comes in handy when my partner and I are on different ends of town but need to keep our spending in check. Plus, the app’s intuitive reports provide a clear picture of where your money is going, helping you spot patterns and adjust as needed.
For shared spending, the useful habit is to agree on category expectations before either person taps to pay. A shared view can help you coordinate, but it cannot settle disagreements about priorities by itself. If one person thinks a category is for household essentials and the other treats it as flexible spending, the numbers may be current while the plan is still unclear. A short conversation about what each category means can prevent that confusion.
Reports are most helpful after you have enough activity to notice a pattern. I wouldn’t overreact to a single unusual week, especially if it includes a one-off expense. Instead, look for a repeatable mismatch: perhaps a category routinely needs more money, or an expense that seemed rare keeps returning. That is a practical cue to change the plan, not evidence that you have failed at budgeting.
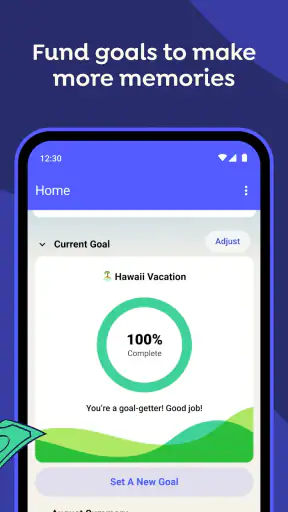
The goals feature is another winner. You can set specific financial targets, like saving for a vacation or paying off debt. YNAB then helps you stay on track with these objectives, gently nudging you to make progress.
A useful way to make a goal feel less abstract is to connect it to a choice you can make each time money arrives. For example, if a trip matters more than upgrading a household item, assigning some available money toward the trip makes that priority visible. The trade-off is that a goal is not extra money: funding one means deciding which other job gets less. I’d keep goals realistic enough that regular bills and basic spending do not become an afterthought.
Design, routine, and the learning curve
The design is sleek and user-friendly, with a clean interface that doesn’t overwhelm you with numbers and charts. It’s all about simplicity, allowing you to focus on what truly matters: managing your money. The vibrant color coding is a nice touch, making it easy to see how much you’ve budgeted, spent, and have left to spend.
That clarity is valuable, but the routine still depends on keeping the budget current. A color or balance only helps if recent spending has been entered or reflected accurately. I’d make a brief check part of an existing habit, such as reviewing purchases after shopping or looking over categories before planning the week. Leaving every adjustment until the end of the month makes the budget less useful for decisions you need to make now.
Common points of confusion
While YNAB is user-friendly, there’s a bit of a learning curve if you’re new to budgeting. However, the app offers a wealth of resources, including workshops and a robust knowledge base, to help you get the hang of things. I found the online community to be a great support system too, with plenty of tips and shared experiences from other users.
The biggest mental shift is that a budget is not a prediction of what you will spend; it is a plan for the money on hand. That distinction can feel awkward if you are used to checking a bank balance and treating the full amount as available. Some of that balance may already have a job, such as rent or a bill due soon. Looking at category amounts instead helps answer whether a particular purchase fits your plan.
Another common snag is trying to make every category precise before using the app. I’d rather begin with a simple, honest plan and revise it as real expenses show where it is unrealistic. It is also worth deciding how you want to handle shared household costs and irregular purchases. Those are personal choices, not settings that can replace a conversation or make the budget automatically match everyone’s priorities.
Who will benefit, and who may prefer something else
I think YNAB suits people who want to make active choices about spending, people dealing with uneven expenses, and households that are willing to check in on a shared plan. It can be especially useful when a bank balance feels misleading because upcoming bills and savings goals are mixed together. Its method gives those dollars distinct purposes, which makes trade-offs easier to see.
On the other hand, if you only want a passive record of transactions, a simpler expense tracker may feel less demanding. Someone who prefers a spreadsheet may also like having complete control over layout and calculations without adopting a specific budgeting method. And if you know you won’t keep categories reasonably up to date, a detailed plan can become frustrating rather than helpful. I would not pick YNAB expecting it to make financial decisions automatically; its value comes from the decisions you make while using it.
Compared with a plain spreadsheet, the app offers a guided structure and a connected experience across phone and computer, while a spreadsheet can be more flexible and easier to adapt to unusual needs. Compared with a basic expense tracker, YNAB puts more emphasis on assigning money before it is spent rather than merely sorting purchases afterward. Neither approach is universally better. If your main need is a record of where money went, tracking may be enough; if you want a repeatable way to decide where available money should go next, the more involved method may earn its place.
Final Thoughts
In a nutshell, YNAB is a fantastic tool for anyone looking to take control of their finances. It’s especially great if you’re looking to get serious about budgeting without feeling overwhelmed. With its real-time sync, powerful goal-setting features, and supportive community, YNAB might just be the financial sidekick you’ve been searching for.
My recommendation is to judge it by whether it helps you make one better decision at a time, not by whether your first budget looks polished. Start with money you have, give the most urgent dollars clear jobs, and adjust when life does not follow the original plan. If that kind of hands-on routine feels reassuring, the app is worth considering. If it feels like one more chore, a simpler tracker or a spreadsheet may fit you better.
So, if you’re ready to give every dollar a job and stop living paycheck to paycheck, why not give YNAB a go? You might just find budgeting isn’t as scary as it seems.
YNAB FAQ
What is YNAB and how does it work?
YNAB, or You Need a Budget, is a personal finance app designed to help users manage their money by assigning every dollar a specific job. It works by encouraging users to plan expenses, prioritize needs, and adjust their budgets as financial situations change. The app emphasizes proactive financial management, promoting savings and financial discipline.
Is YNAB secure for managing my financial information?
Yes, YNAB takes security seriously, employing bank-level encryption to protect your financial data. The app does not store your bank login details and uses read-only connections to sync your transactions. Regular security audits and updates further ensure that your information remains safe and protected from unauthorized access.
Can YNAB be used on multiple devices and platforms?
Absolutely! YNAB is available on multiple platforms, including iOS, Android, Windows, and macOS. You can access your budget information across all your devices, ensuring that you can manage your finances seamlessly whether you're at home or on the go. The app syncs data automatically to keep everything up to date.
Does YNAB offer any features for beginners?
Yes, YNAB is designed with beginners in mind. It offers a range of educational resources, including workshops, webinars, and tutorials, to help new users get started. The app's intuitive interface and step-by-step guidance make it easy for those new to budgeting to create and manage their financial plans effectively.
Is there a cost associated with using YNAB?
YNAB operates on a subscription model, offering a 34-day free trial for new users to explore its features. After the trial, users can choose a monthly or annual subscription plan. While there is a cost, many users find the expense worthwhile due to the financial clarity and savings the app helps them achieve.
The Best Parts of YNAB
Things to Keep in Mind About YNAB
Get YNAB in Another Language